Car Loans Australia :: Articles

Pros and Cons of Switching Your Mortgage Lender

What are the pros and cons of switching mortgage lenders in Australia?

Pros and Cons of Switching Your Mortgage Lender

The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.

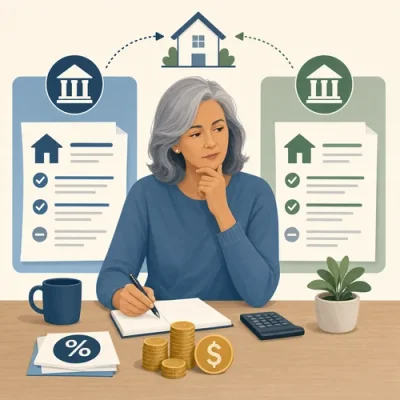
The concept of home loan refinancing has gained significant popularity among Australian homeowners in recent times, with hundreds of thousands of individuals switching mortgage lenders in search of better home loan rates over the past 12 months alone.

There are numerous reasons for refinancing, including speculation about interest rate hikes, an array of lending options, dissatisfaction with current lender's service, the need for more mortgage flexibility, and the opportunity to pay off a home loan sooner. Some individuals also refinance to consolidate high-interest debt into a lower paying loan such as a mortgage or to tap into the equity in their homes to fund renovations or other investments.

However, refinancing can come with substantial costs. The expenses can run into the tens of thousands, including valuation fees, early discharge fees, application fees, mortgage insurance, and stamp duty (depending on your State).

Refinancing can also be a time-consuming process as one has to deal with two lenders instead of one and the associated paperwork.

While a mortgage broker can help match you with the right lender and manage the process, it's important to note that brokers receive an upfront fee of around 0.4% of the loan amount and ongoing commissions that may represent 0.2% of the loan balance.

Before refinancing, it's advisable to contact your current lender to see if they can offer you a better deal. Additionally, one should consider the costs of refinancing and the time it will take to recoup them.

If you're planning to sell the property in the short-term, refinancing may not be the best option, but if you're planning to keep it for the long-term, the costs might be worth the hassle. If your calculations show that you can save money by switching lenders, remember to ask if your current lender can match the deal you are considering.

Published: Thursday, 29th Mar 2007
Author: 2

Rate this article

0 Comments

No comments yet. Be the first to share your thoughts.


Car Loans Articles

Secured vs Unsecured Car Loans in Australia
Buying a car is a significant financial decision, and the type of loan you choose can affect your repayments, borrowing costs and financial flexibility. In Australia, car loans are commonly discussed as either secured or unsecured, depending on whether the vehicle or another asset is used as collateral. Understanding how each loan type works can help you compare terms, ask better questions and consider the risks before committing to a finance agreement. - read more
How Credit History Affects Car Loan Approval in Australia
Your credit history can influence whether a lender considers your car loan application, the rate you are offered and the conditions attached to the loan. This guide explains what Australian lenders may look for, how impaired or limited credit history can affect an application, and how to prepare before applying. - read more
The Complete Checklist for Choosing a Car Loan Provider in Australia
Finding the right car loan in Australia can be just as critical as selecting the car itself. Car finance, though a common undertaking, involves nuanced decisions that can have a significant impact on your financial future. - read more
How to Compare Car Loans: A Step-by-Step Guide for Australian Buyers
When planning to take out a car loan, it is crucial to start by understanding your budget. Consider how much you can realistically afford to borrow without straining your finances. Assessing your monthly income and expenses will help you arrive at a sensible figure, ensuring you don't overcommit. - read more
Consumer Protections and Legal Obligations for Car Loans in Australia
Car loans in Australia are subject to consumer credit laws, disclosure rules and dispute resolution pathways. This guide explains key protections, lender and broker obligations, borrower responsibilities, comparison rates, hardship rights and what to check before signing a finance contract. - read more

Finance News

Green Car Loan Deals Are Growing, But the Fine Print Still Matters
17 Sep 2026: Paige Estritori
Green car finance is becoming a more visible part of Australia’s car loan market, with lenders continuing to promote discounted rates for eligible electric, hybrid and other lower-emission vehicles. For buyers weighing up a new EV, plug-in hybrid or fuel-efficient model, the headline appeal is obvious: a lower rate can reduce the cost of borrowing and may make a higher purchase price feel more manageable. - read more
Why Sharper New-Car Offers Still Need a Loan Check
03 Sep 2026: Paige Estritori
Australia’s new-car market is showing more signs of competition, with recent industry updates pointing to sharper drive-away offers, run-out campaigns and finance-led promotions across selected brands. For buyers, that can make the showroom feel more attractive than it did during the tight-supply years, when wait times and limited stock gave sellers more pricing power. - read more
Softer Used-Car Prices Could Shift Finance Decisions
27 Aug 2026: Paige Estritori
Australia's used-car market appears to be moving into a more balanced phase, with recent industry updates pointing to improved vehicle availability and less pressure on prices across some mainstream segments. That is welcome news for buyers who spent the past few years dealing with limited stock, long new-car wait times and unusually firm second-hand values. - read more
What the Latest RBA Rate Hold Means for Car Buyers
13 Aug 2026: Paige Estritori
The Reserve Bank of Australia's latest decision to leave the cash rate unchanged keeps car buyers in a familiar holding pattern: borrowing costs are not rising sharply, but they are not easing quickly either. For households planning a new or used vehicle purchase, that means the focus should remain on preparation, comparison and affordability rather than waiting for a dramatic rate shift. - read more
What ASIC’s Car Loan Review Means for Australian Buyers
23 Jul 2026: Paige Estritori
Australia’s car finance market is sending buyers two important messages at once. Recent July rate snapshots show some secured car loans advertised from around the mid-five per cent range for strong-credit borrowers, suggesting competition is still alive for well-prepared applicants. At the same time, ASIC’s 24 June 2026 review of motor vehicle finance has put the spotlight on fees, third-party sales channels and borrower outcomes. - read more

Need Help Finding a Loan?
Get a free car loan eligibility assessment and compare offers tailored specifically to your circumstances.

Stay informed with MoneyTips

Get practical financial information, news, guides and resources.

All finance quotes are provided free (via our secure server) and without obligation.
We respect your privacy.

Knowledgebase
Private Mortgage Insurance (PMI):
A type of insurance that a borrower might be required to purchase as a condition of a conventional mortgage loan, if the down payment is less than 20% of the property value.